Introducing Databento Core Indices
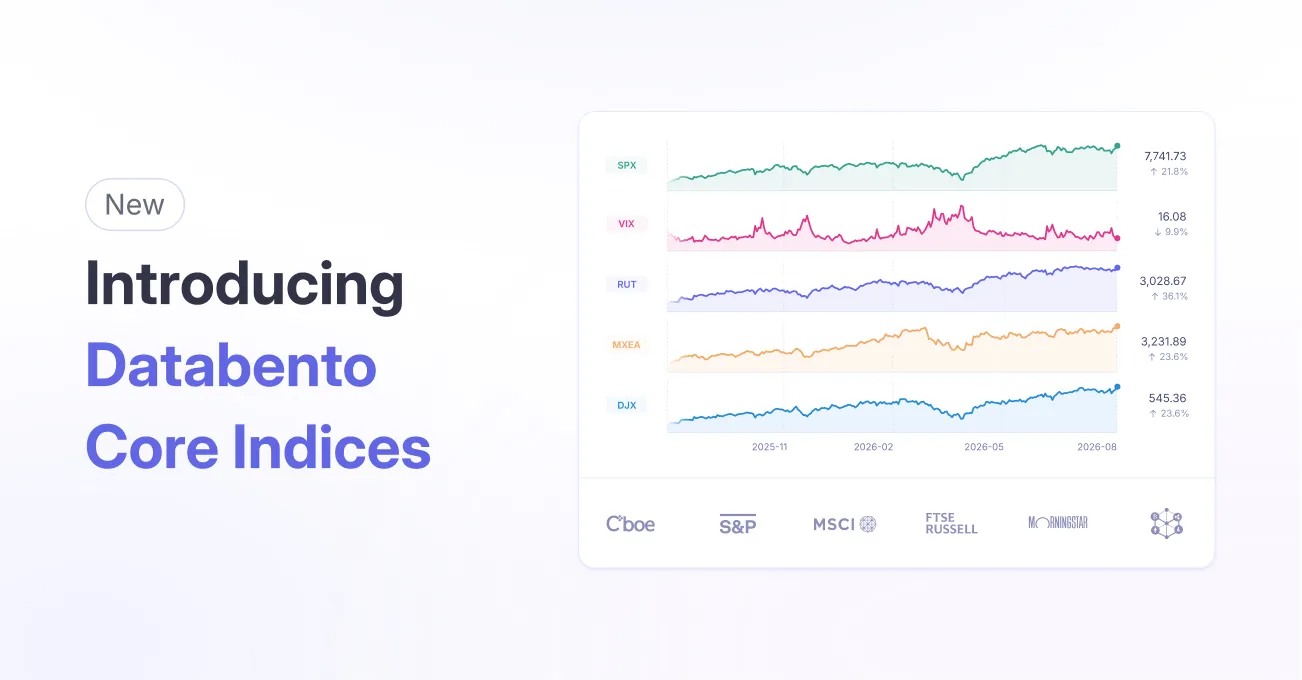
We're excited to announce Databento Core Indices, our new service that provides real-time and historical data for more than 2,500 indices.
The dataset covers major equity benchmarks such as SPX and RUT, volatility indices such as VIX, options settlement values, ETF indicative values, and crypto indices.
A complete list of indices is available in our catalog. See pricing to explore subscription plans, which start at $99/month.
Databento Core Indices is sourced from the Cboe Global Indices Feed (CGIF), Cboe's primary feed for real-time and end-of-day index values. CGIF disseminates indices calculated by Cboe and other index providers, including S&P Dow Jones, FTSE Russell, MSCI, and Morningstar.
Coverage includes:
- Equity benchmarks: S&P 500 (SPX), Russell 2000 (RUT), MSCI EAFE and Emerging Markets, Cboe UK and Europe indices, and more than 1,400 Morningstar indices.
- Volatility indices: VIX and its variants, including VIX1D through VIX1Y, plus VVIX, SKEW, VXN, and RVX.
- Options settlement and strategy indices: Official SPX and VIX settlement values (SET and VRO), alongside strategy benchmarks such as BXM and PUT.
- ETF intraday indicative values (iNAVs): Nearly 300 ETFs, including TQQQ and SQQQ.
- Crypto indices: Cboe RealPrice indices and cryptocurrency benchmarks from Coin Metrics, CoinRoutes, and Lukka.
Market participants use index data for portfolio valuation, performance benchmarking, and volatility monitoring. ETF iNAVs also provide intraday estimates of an ETF's underlying value for comparison with its market price.
Several of these indices underlie options traded on Cboe, including SPX, VIX, the Russell 2000, and select MSCI indices. Core Indices includes the official settlement values for SPX (SET) and VIX (VRO). Same-day expiration (0DTE) contracts account for a significant share of SPX options trading, where intraday index movements are particularly important for options valuation and heading.
We capture CGIF directly in Equinix NY4 and normalize all seven channels into a single dataset with the ID DBIX.CORE.
Because index values are calculated rather than traded, price updates have no associated order book data or trading volume. Update frequency varies by index: SPX, most iNAVs, and the crypto indices update every second, while VIX, RUT, MSCI indices, and most others update about every 15 seconds.
Historical coverage begins November 23, 2025. Data is available at usage-based rates starting at $10.00/GB or included with any Databento Core Indices subscription.
The following example requests one day of SPX index values using our Python client library:
import databento as db

client = db.Historical("$YOUR_API_KEY")

data = client.timeseries.get_range(
    dataset="DBIX.CORE",
    schema="trades",
    symbols=["SPX"],
    start="2026-10-07",
    end="2026-10-08",
)

df = data.to_df()
print(df[["symbol", "price"]])
Real-time Databento Core Indices data is included with a Standard or Unlimited plan.
The following example streams SPX and VIX index updates:
import databento as db

client = db.Live(key="$YOUR_API_KEY")

client.subscribe(
  dataset="DBIX.CORE",
  schema="mbp-1",
  symbols=["SPX", "VIX"],
)

for record in client:
  print(record)